What an Emergency Fund Actually Does for Your Household
Emergency funds are more than a savings cushion. This explainer covers how they work, how much families typically need, and why timing matters.
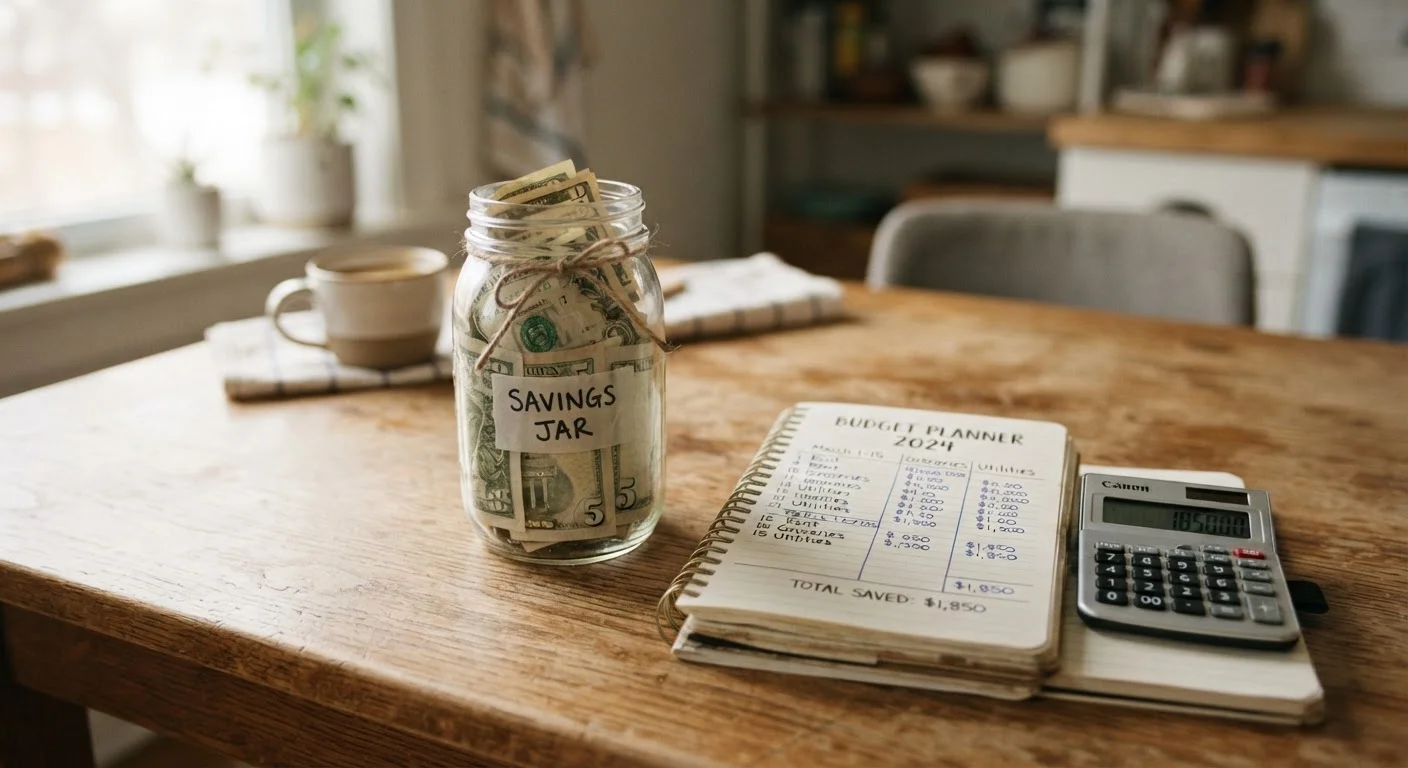
Photo: appropriateanswers.com editorial
—— In This Article
Key Takeaways
- An emergency fund covers unplanned costs without requiring new debt.
- Most financial guidance suggests three to six months of essential expenses as a target.
- The fund should be kept in a liquid account separate from daily spending money.
- Starting with a small, fixed goal makes the habit easier to build consistently.
- An emergency fund and a sinking fund serve different purposes and should not be merged.
What an emergency fund actually does
An emergency fund does one concrete thing: it gives a household a way to pay for an unexpected, necessary cost without borrowing money or disrupting long-term savings. That distinction matters because both of those alternatives carry real costs. A credit card balance accrues interest. An early withdrawal from a retirement account may trigger taxes and penalties, plus it removes compounding time that cannot be replaced.
The fund works as a circuit breaker. When a crisis hits, the family pays from the reserve, absorbs the loss, and then rebuilds the reserve over the following months. Without it, a single setback can create a chain reaction: debt taken on to cover one emergency makes the next month's budget tighter, which makes the next emergency harder to absorb, and so on.
To see how an emergency fund fits within a broader household financial plan, the family budget starting point explains the core concepts and frameworks that make room for saving in the first place.
How much is enough
The widely cited range is three to six months of essential expenses, not total income. Essential expenses include housing costs, utilities, groceries, transportation to work, health insurance premiums, and minimum debt payments. Discretionary spending, dining out, streaming subscriptions, and similar items are not part of the calculation.
A single-income household with children typically needs a larger cushion than a dual-income household with no dependents, because the financial exposure is greater if that one income stops. Similarly, a household where one member has a chronic health condition may face larger unexpected medical costs and should account for that when setting a target.
~37%
Adults who could not cover a $400 emergency in cash
According to the Federal Reserve's 2023 Report on the Economic Well-Being of U.S. Households, roughly 37% of U.S. adults said they would struggle to cover an unexpected $400 expense using cash or its equivalent.
3-6 months
Recommended emergency fund coverage range
Consumer financial education resources, including those published by the Consumer Financial Protection Bureau, generally recommend covering three to six months of essential household expenses.
$500
Common recommended starting savings milestone
Many financial educators suggest an initial target of $500 to $1,000 as a first emergency fund milestone because it covers the most common small unexpected expenses without requiring years of saving to reach.
Calculating your own number starts with listing monthly essential expenses and multiplying by the number of months you are targeting. The needs, wants, and savings explainer covers how to separate essential from discretionary spending, which is the foundation of that calculation.
Emergency funds versus sinking funds
These two savings tools are often confused, but they solve different problems. A sinking fund is built in advance for an expense you know is coming but do not pay monthly, such as annual car registration, holiday gifts, or back-to-school supplies. The sinking funds explainer goes deeper on that approach.
An emergency fund covers what you cannot predict or schedule. If the furnace breaks in January, that is an emergency. If the car registration is due every October, that is a sinking fund situation. Keeping the two pools separate prevents a family from mistaking planned spending for available reserves, which is how emergency funds get depleted before an actual emergency arrives.
Building the fund without disrupting the budget
The most common obstacle is not the savings rate but the starting point. A target of six months of expenses can feel distant enough to delay action. Setting an initial goal of $500 or $1,000 makes the first phase concrete and achievable. Once that milestone is reached, the contribution habit is already in place, and the target can be raised.
Automating the transfer on payday removes the decision from the monthly routine. A fixed amount, even a small one, moves to the emergency fund before it becomes available for spending. Over time, windfalls such as tax refunds or annual bonuses can accelerate the process without changing the monthly budget at all.
The monthly money habits guide outlines low-effort routines that help families stay consistent with savings goals, including building and maintaining an emergency reserve.
One often-overlooked intersection involves health costs. Unexpected medical bills are among the most common emergency fund triggers for families. Understanding how a Health Savings Account works alongside a high-deductible plan may reduce the frequency of large out-of-pocket medical surprises, which in turn reduces the pressure on an emergency fund. And knowing when to use an urgent care clinic rather than an emergency room, as covered in the urgent care vs. ER guide, can significantly lower the bill when a health issue does arise.
This article is for general informational and educational purposes only and does not constitute personalized financial advice. Consult a qualified financial professional for guidance specific to your household's circumstances.
Frequently Asked Questions
Smart Family Finance Editorial Team
Smart Family Finance Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile