Sinking Funds: Turning Predictable Surprises into Non-Events
Car repairs, back-to-school shopping, holiday gifts: learn how sinking funds let families plan for irregular costs before they arrive.
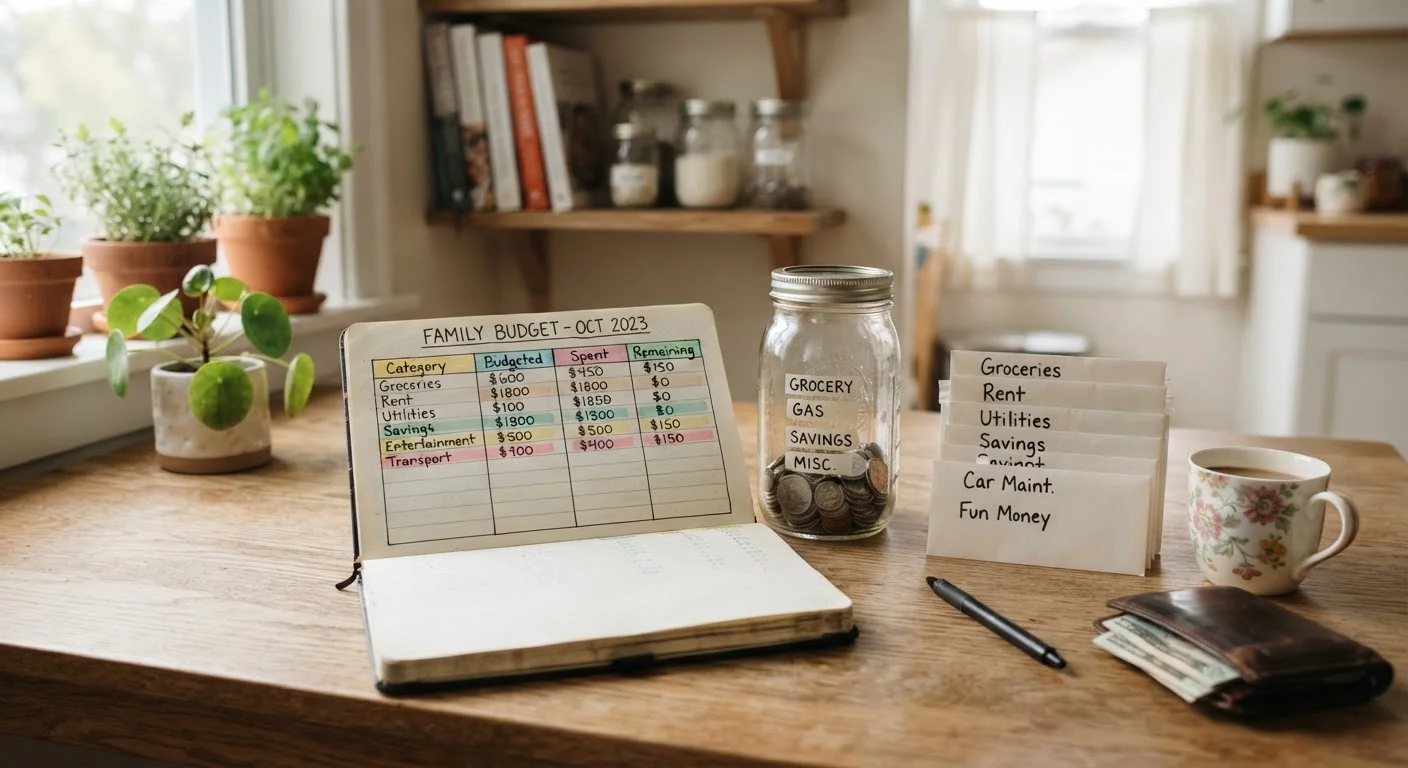
Photo: appropriateanswers.com editorial
—— In This Article
Key Takeaways
- A sinking fund is money you set aside in advance for a known future expense.
- Sinking funds are separate from emergency funds, which cover unexpected costs.
- Dividing a large annual cost by 12 gives you a monthly contribution target.
- Even small monthly amounts, saved consistently, prevent reliance on credit for irregular bills.
- Common sinking fund categories include car repairs, holidays, back-to-school, and travel.
What a sinking fund actually is
A sinking fund is a dedicated pool of money you build gradually to cover a cost you can already predict. You know the car will need new tires eventually. You know December will arrive. You know back-to-school season produces a stack of supply lists. None of these are surprises in any real sense, yet millions of families scramble to cover them every year because no advance saving happened.
The phrase sounds technical, but the idea is simple: pick a future expense, estimate its cost, divide by the number of months until you need the money, and save that amount each month. When the bill arrives, the money is already there.
A sinking fund is not the same as an emergency fund. An emergency fund covers genuinely unpredictable events: a job loss, a medical crisis, a furnace that fails without warning. Sinking funds cover costs that are irregular but foreseeable. Mixing the two purposes into one account makes it harder to know whether you are financially prepared or quietly draining your safety net.
If you want a broader framework before setting up individual sinking funds, the building blocks of a family spending plan article covers the vocabulary and structure worth understanding first.
How to set up and run your sinking funds
The steps below walk through the full process. Each one is achievable in a single evening. You do not need special software or a financial background.
What you will need
List every irregular expense your family faces
Write down every cost that does not appear on your monthly bills but does appear at some point during the year. Common examples include:
- Car maintenance and repairs
- Holiday gifts and decorations
- Back-to-school supplies and clothing
- Annual insurance premiums
- Family vacation
- Medical copays and dental visits
- Home maintenance (HVAC filters, pest control, gutter cleaning)
Do not edit the list at this stage. Capture everything you can think of, then add anything you forgot by scanning last year's bank or credit card statements.
Estimate the annual cost for each item
Assign a realistic dollar amount to each expense on your list. Use past receipts where you have them. For costs you have not yet faced, look at general price ranges from multiple sources rather than assuming a best-case number. It is better to save slightly more than you need than to come up short when the bill arrives.
Group small related expenses together if managing too many separate funds feels unwieldy. For example, combine school supplies, sports registration fees, and back-to-school clothing into one 'school year' fund.
Calculate your monthly contribution for each fund
Divide each annual estimate by the number of months until you need the money. If you are starting a holiday fund in January and need the money in November, divide by 10. If you are starting a car maintenance fund and the need is ongoing, divide by 12.
Example: a $600 car repair reserve divided by 12 months equals $50 per month. A $900 holiday budget started in February and needed by late November equals $100 per month over 9 months.
Open a dedicated savings account (or accounts)
Move sinking fund money out of your main checking account so you do not accidentally spend it. Many families use a single high-yield savings account and track each fund's balance in a simple spreadsheet. Others open separate savings accounts, one per fund, if their bank allows multiple free accounts.
Either approach works. The goal is a clear boundary between money earmarked for a future purpose and money available to spend today.
Review and adjust each fund at least twice a year
Costs change. A child joins a new sport, a car ages out of warranty, or a planned trip grows in scope. Set a calendar reminder every six months to check each fund's projected balance against its target. Adjust the monthly contribution if your estimate has changed.
When you spend from a fund, reset the contribution schedule so the account refills before the next time you need it.
Once your sinking funds are running, you may find the same discipline transfers naturally to travel. The principles for stretching a family travel budget pair well with a dedicated vacation sinking fund, because you already know roughly what the trip will cost before you book.
For context on why these structural habits matter, why families overspend despite good intentions explains the psychological and systemic patterns that trip up even careful budgeters.
Start with one or two funds
Families who try to fund every category at once often give up within two months because the total monthly commitment feels overwhelming. Pick the one or two expenses that caused the most financial stress last year and build those funds first. Add more categories as your budget adjusts.
Fitting sinking funds into your existing budget
Sinking fund contributions are a budget line, not an afterthought. List them alongside rent, groceries, and utilities when you plan each month. This framing matters because families often treat irregular expenses as optional until they become urgent, which is exactly when paying for them is most painful.
If your current budget uses categories and spending limits, envelope budgeting in a digital world shows how the same logic works whether you use cash envelopes or a spreadsheet. Sinking funds map directly onto that structure.
Sustaining the habit month after month is where most people slip. The monthly money habits that keep a family budget on track article offers low-effort routines for reviewing progress and catching drift early.
Travel is one area where sinking funds pay off particularly clearly. Families who save in advance for vacations spend less overall because they make calmer decisions. Reactive vacation spending, by contrast, drives many of the patterns described in how families accidentally overspend on vacation.
This article provides general financial education and is not personalized financial advice. Consult a qualified financial professional for guidance specific to your household's circumstances.
Smart Family Finance Editorial Team
Smart Family Finance Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile