Needs, Wants, and Savings: The Building Blocks of a Family Spending Plan
A clear reference to the key terms every family encounters when building a budget, from discretionary income to debt-to-income ratio.
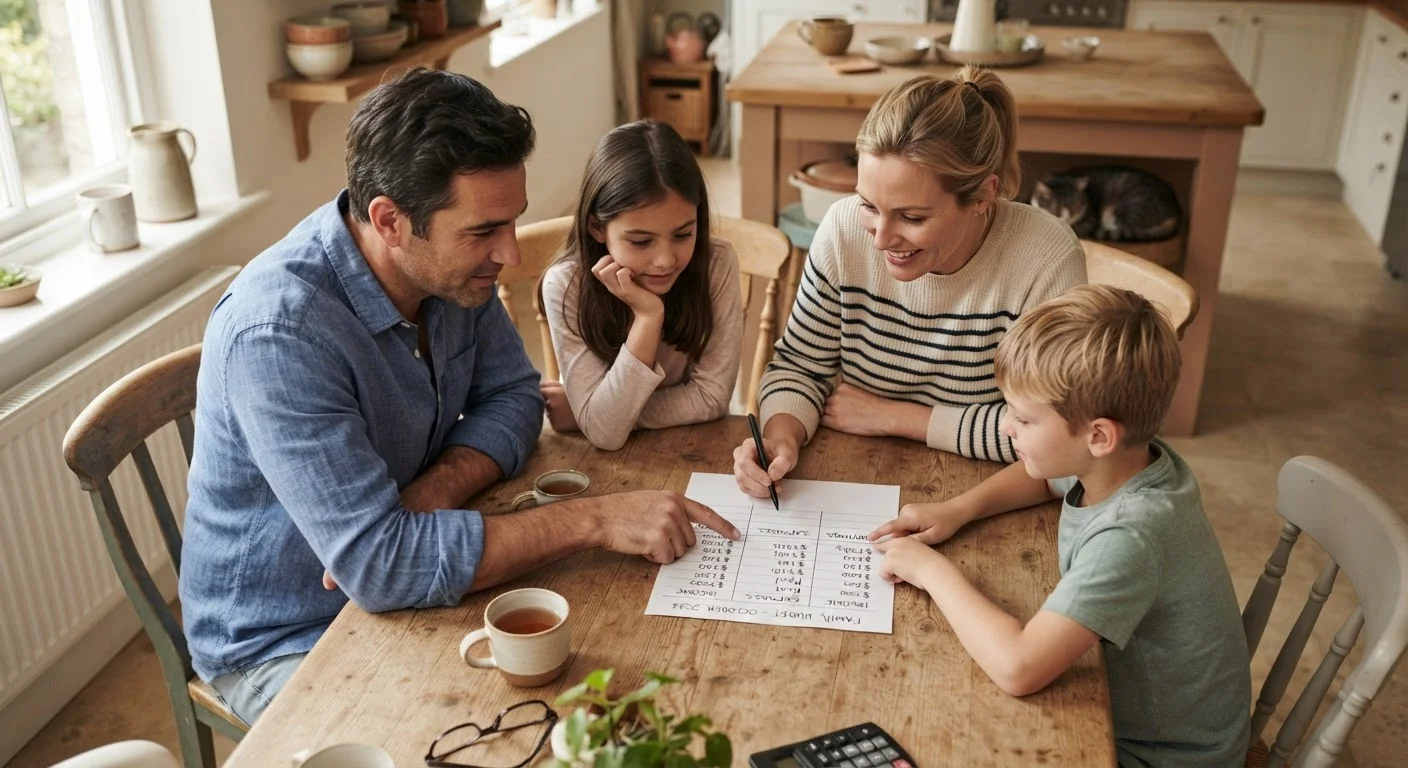
Photo: appropriateanswers.com editorial
—— In This Article
Why these terms matter before you build a budget
A budget is only as clear as the language behind it. When families sit down to organize their finances, they often hit a wall of terms: discretionary income, fixed expenses, debt-to-income ratio. These are not complicated ideas, but without plain definitions, they slow everything down. This reference covers the terms you will encounter most often, so you can move from confusion to a working plan. For a broader introduction to budgeting as a household, see the family budget starting point.
The three concepts at the center of most family spending plans are needs, wants, and savings. Everything else in a household budget connects back to those three categories.
Needs
Expenses that are necessary for basic household function, including housing, utilities, groceries, transportation to work, and health insurance. Without these, the household cannot operate safely or meet its obligations.
Wants
Spending that improves comfort or enjoyment but is not required for basic function. Streaming subscriptions, dining out, and recreational activities fall into this category. Wants are the first place most families look when they need to reduce spending.
Savings
Money set aside from income for future use, whether for an emergency fund, a specific goal such as a home purchase, or long-term retirement. In a budget, savings is often treated as a fixed outflow rather than whatever remains after spending.
Fixed expenses
Costs that are the same amount each month, such as rent or mortgage payments, car loan payments, and insurance premiums. Because they do not change, they are the easiest to plan for.
Variable expenses
Costs that change month to month, such as groceries, gas, utilities, and clothing. These require more active tracking because the amount is not predictable.
Discretionary income
The money remaining after taxes and essential expenses have been paid. It covers wants and additional savings. Discretionary income is not the same as take-home pay: fixed needs come out first.
Gross income
Total earnings before any taxes, insurance premiums, or retirement contributions are deducted. Gross income is often used when calculating ratios such as the debt-to-income ratio.
Net income
The amount actually deposited into your account after taxes and other deductions. Most household budgets are built around net income because it reflects the money you actually have to spend.
Debt-to-income ratio (DTI)
The percentage of gross monthly income that goes toward debt payments, including mortgage or rent, car loans, student loans, and minimum credit card payments. Lenders use this figure to assess borrowing capacity.
Emergency fund
A reserve of liquid savings intended to cover unexpected expenses such as medical bills, car repairs, or temporary job loss without requiring the family to take on debt.
Budget surplus
The positive difference when income exceeds total planned spending for a period. A surplus can be redirected to savings, debt payoff, or a future expense.
Budget deficit
The negative difference when planned or actual spending exceeds income for a period. A recurring deficit typically means the household needs to reduce spending, increase income, or both.
Core budget terms, defined
The table below organizes the most common budgeting concepts by how they function in a household plan. Once you can place a dollar amount into one of these categories without hesitating, building and adjusting a budget becomes much faster.
| Needs (typical share of after-tax income) | Around 50% (50/30/20 budgeting framework) |
| Wants (typical share of after-tax income) | Around 30% (50/30/20 budgeting framework) |
| Savings and debt repayment (typical share) | Around 20% (50/30/20 budgeting framework) |
| Recommended emergency fund size | 3 to 6 months of essential expenses (Consumer Financial Protection Bureau general guidance) |
| DTI threshold often flagged by lenders | 43% or above (General mortgage lending guidance) |
| Fixed vs. variable expenses | Fixed: same each month. Variable: changes month to month. |
Two budgeting frameworks use these categories differently. The 50/30/20 rule divides after-tax income into 50 percent needs, 30 percent wants, and 20 percent savings and debt repayment. Zero-based budgeting assigns every dollar a specific purpose so that income minus all allocations equals zero. A side-by-side comparison of both methods can help you decide which fits your household's income pattern and lifestyle.
Your debt-to-income ratio (DTI) is a number lenders use to assess how much of your gross monthly income already goes toward debt payments. A lower DTI generally signals more room in the budget for saving or borrowing responsibly. Most financial guidance treats a DTI above 43 percent as a point of concern, though individual circumstances vary. For questions about your own DTI and what it means for your financial situation, a licensed financial adviser or housing counselor can give guidance specific to your circumstances.
This article is for general informational and educational purposes only and is not personalized financial advice. Consult a qualified financial professional for guidance suited to your specific situation.
Putting the terms to work
Knowing the vocabulary is a starting point, not a finish line. Families that make real progress tend to do a few specific things: they track actual spending against planned spending at least once a month, they separate fixed from variable expenses before deciding where to cut, and they treat savings as a scheduled outflow rather than what is left over.
Variable expenses are the most common source of budget drift. Groceries, gas, and utility bills shift month to month, which makes them hard to plan precisely. One approach is to calculate a three-month average for each variable category and use that number as your planned amount. Overspending in a given month becomes visible immediately, and you can adjust the next month. Structural and psychological traps that quietly drain family budgets are also worth understanding, because tracking alone does not always fix the root cause.
Emergency funds deserve specific mention. Financial guidance from organizations such as the Consumer Financial Protection Bureau generally recommends keeping three to six months of essential expenses in an accessible savings account. That fund is not the same as a long-term savings goal: it is a buffer that keeps an unexpected car repair or medical bill from becoming debt. Families building this fund for the first time often start with a smaller target, such as one month of fixed expenses, and grow from there.
For families thinking about health-related savings vehicles, a plain-language overview of Health Savings Accounts covers how they work alongside a high-deductible plan and what general tax advantages may apply. Building consistent money habits around these tools takes time. Monthly routines that keep a family budget on track offers practical steps that fit into an ordinary week without requiring a financial overhaul.
Smart Family Finance Editorial Team
Smart Family Finance Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile