Zero-Based Budgeting vs. the 50/30/20 Rule: Which Works for Families?
Two of the most popular household budgeting methods compared side by side, so you can choose the approach that fits your family's income and lifestyle.
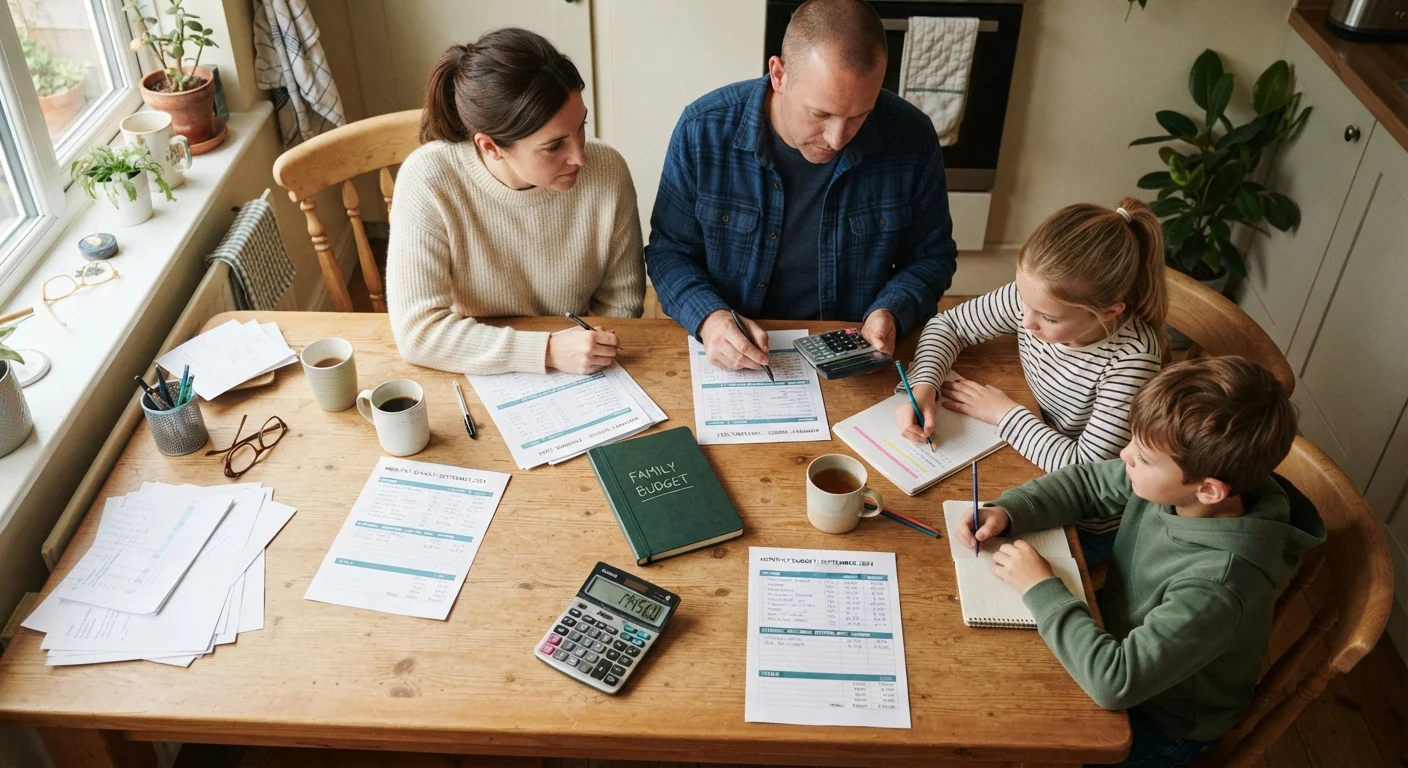
Photo: appropriateanswers.com editorial
—— In This Article
Key Takeaways
- Zero-based budgeting assigns every dollar of income to a specific category until nothing is unallocated.
- The 50/30/20 rule divides after-tax income into three broad buckets: 50% needs, 30% wants, 20% savings or debt.
- Zero-based budgeting requires more time each month but gives families granular control over spending.
- The 50/30/20 rule is faster to maintain but may be too loose for households with tight or irregular income.
- Both methods work: the better choice depends on your income stability, available time, and financial goals.
How each method works
Zero-based budgeting (ZBB) starts with your total monthly income and requires you to assign every dollar to a category: groceries, rent, car payment, school supplies, emergency fund, and so on. When your allocations add up to zero remaining, the budget is complete. No dollar sits unaccounted for. The method was popularized in personal finance by author Jesse Mecham through the YNAB system, though the underlying concept predates any particular product or app.
The 50/30/20 rule divides your after-tax income into three groups. Fifty percent goes to needs (housing, utilities, food, transportation, insurance). Thirty percent goes to wants (dining out, streaming services, family activities). Twenty percent goes to savings or debt repayment. Senator Elizabeth Warren and her daughter Amelia Warren Tyagi outlined this framework in their 2005 book All Your Worth. The percentages are targets, not strict rules, and most households adapt them to fit their reality.
Before choosing between them, it helps to have a clear picture of your household income and spending categories. Our plain-English starting guide to family budgets covers those core concepts if you are new to the process.
Side-by-side comparison
The two methods differ most in the time they require and the level of detail they produce. Here is how they compare across the dimensions that matter most to families.
| Criterion | Zero-Based Budgeting | 50/30/20 Rule |
|---|---|---|
| Monthly setup time | 30 to 60 minutes | 5 to 15 minutes |
| Category detail | Every expense named individually | Three broad buckets |
| Best income type | Variable or irregular | Stable, predictable salary |
| Flexibility | Fully customizable each month | Fixed percentages, minor adjustments |
| Learning curve | Moderate to steep | Low |
| Debt payoff focus | Strong: explicit allocation required | Included in 20% savings bucket |
| Ongoing maintenance | Requires regular check-ins | Monthly review sufficient |
For a deeper look at the vocabulary that comes up in both methods, including terms like discretionary income and debt-to-income ratio, see our reference on needs, wants, and savings as budget building blocks.
Where zero-based budgeting works well for families
Families with variable income get the most from ZBB. A household where one parent freelances, earns commissions, or works seasonal hours cannot rely on last month's numbers. Starting the budget fresh each month with the actual income figure keeps the plan grounded in reality rather than optimism.
ZBB also suits families actively reducing debt. When every dollar needs a named destination, it becomes harder to let money drift toward low-priority spending without noticing. The method creates a visible, documented record of where trade-offs happened, which can help couples stay aligned on financial priorities.
The main cost is time. Setting up a zero-based budget typically takes 30 to 60 minutes at the start of each month, plus brief check-ins when unexpected expenses arise. Families who find that workload sustainable tend to see strong results.
74%
Americans living paycheck to paycheck
A 2023 LendingClub and PYMNTS survey found that roughly 74% of US consumers reported living paycheck to paycheck at some point during the year, underlining why granular budgeting methods matter.
30 min
Typical monthly ZBB setup time
Personal finance educators generally estimate that a zero-based budget for a household of four takes 30 to 60 minutes to build at the start of each month.
20%
Savings and debt target in 50/30/20
The 50/30/20 framework reserves 20% of after-tax income for savings and debt repayment, a target that aligns with widely cited general guidance on household saving rates.
Where the 50/30/20 rule works well for families
The 50/30/20 rule fits households with stable, predictable take-home pay. When your salary is consistent, the percentages stay roughly accurate from month to month, and the budget needs little adjustment.
Because the categories are broad, the method is forgiving. A family does not need to decide in advance whether a school field trip counts as a "want" or an "education" line item. It falls under the 30% bucket and moves on. That flexibility reduces the friction that causes many people to abandon a budget entirely.
One honest limitation: a 30% wants allowance on a median US household income leaves meaningful room for spending that may not align with longer-term goals. Families using this method benefit from pairing it with a monthly review. Our guide to monthly money habits that keep a budget on track covers practical routines that take under an hour.
If you have tried envelope budgeting before, the 50/30/20 rule operates on similar category logic but without the physical or digital envelopes. Our article on envelope budgeting adapted for digital payments explores that comparison directly.
Adapting either method to your family's situation
No budgeting method works exactly as written for every household. A family of five in a high cost-of-living city may find that housing alone consumes more than 50% of take-home pay, making the 50/30/20 percentages a poor starting point. In that case, adjusting the needs bucket to 60% and trimming wants to 20% is reasonable, provided savings still get a deliberate allocation.
Families using ZBB who find the monthly rebuild overwhelming can simplify by creating a master template budget, then only adjusting the categories that change each month. Most months, mortgage, car payment, and insurance stay fixed; only groceries, gas, and variable expenses need updating.
Both methods pair well with the habits that help families manage travel and other irregular large expenses. Allocating a small monthly amount to a named "travel" or "vacation" category, whether inside a ZBB plan or within the 50/30/20 wants bucket, prevents those costs from landing as surprises. See our overview of principles for stretching a family travel budget for how that fits into broader spending management.
This article is for general informational and educational purposes only and does not constitute personalized financial advice. Consult a licensed financial professional for guidance specific to your household's circumstances.
Smart Family Finance Editorial Team
Smart Family Finance Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile