Monthly Money Habits That Keep a Family Budget on Track
Consistent, low-effort routines that help families catch problems early, reduce financial stress, and make progress toward savings goals month after month.
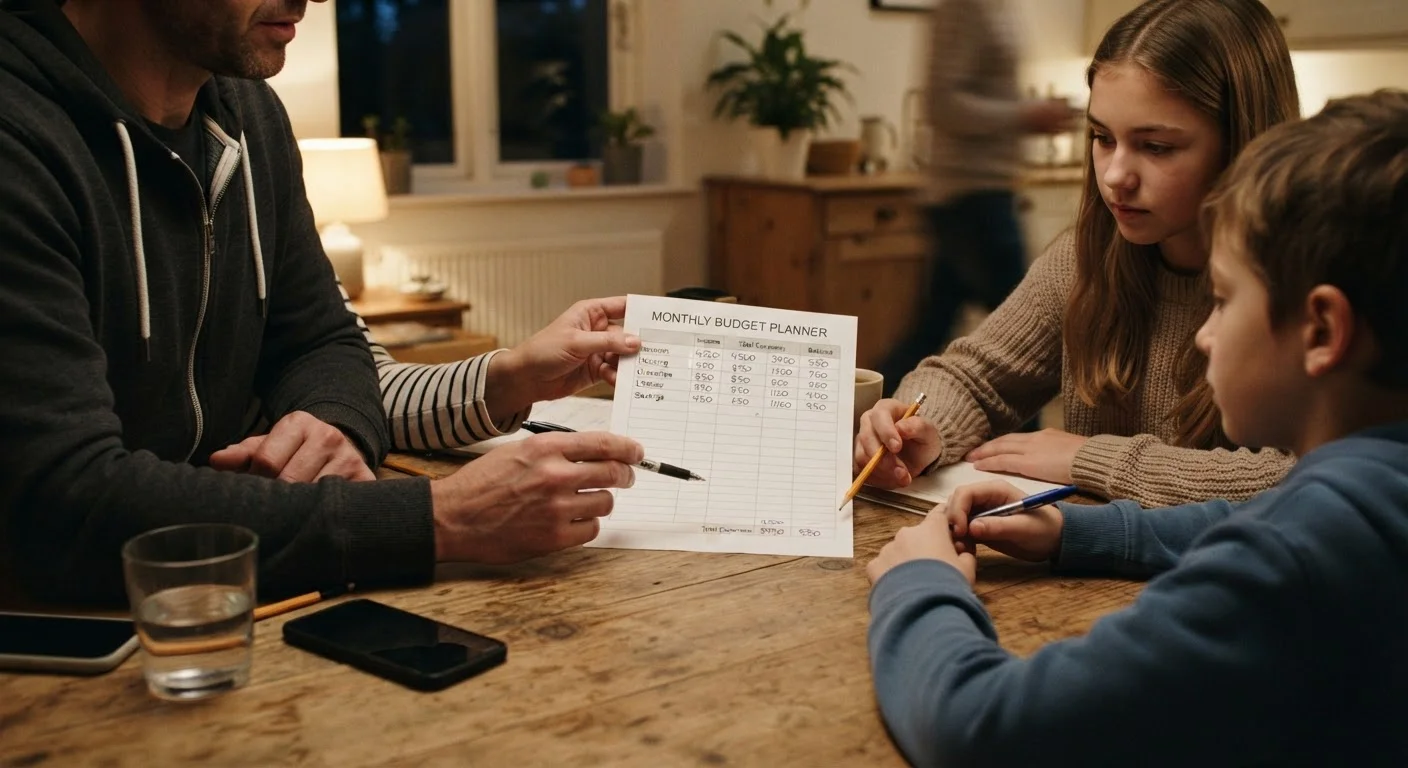
Photo: appropriateanswers.com editorial
—— In This Article
Key Takeaways
- A short monthly check-in catches overspending before it compounds across several pay periods.
- Automating savings transfers removes the decision-making that causes most families to delay saving.
- Reviewing subscriptions and recurring charges once a month often uncovers fees that went unnoticed.
- Sinking funds convert irregular large expenses into predictable monthly line items.
- Involving all adults in a household in the budget review reduces financial blind spots.
Why monthly habits outperform annual planning
A yearly budget sits in a drawer. A monthly habit lives in your actual financial life. Families who check in with their money once a month catch problems when they are still small: a category that crept $40 over budget is manageable; one that ran over for six months without notice is a real setback.
Monthly habits also match how most households actually receive income and pay bills. Aligning your review cycle to your billing cycle means you are always working with current numbers, not outdated estimates from January.
If you are new to building a household budget, start with the core concepts before adding a monthly review routine on top. The practices below assume a basic budget is already in place.
Core practices that make a monthly budget stick
The following habits are low-effort individually. Their combined effect is that money problems surface quickly rather than silently growing.
Schedule a fixed monthly budget review date and treat it as non-negotiable.
Without a set date, the review gets pushed back indefinitely. A recurring calendar appointment removes the friction of deciding when to do it. Families who review on a fixed schedule catch category overruns while they can still adjust spending for the rest of the month.
Automate your savings transfer on payday before other spending happens.
Money that sits in a checking account tends to get spent. Moving a set amount to savings on the same day income arrives means saving happens before discretionary choices do. This removes willpower from the equation entirely.
Audit every recurring charge and subscription once per month.
Streaming services, app subscriptions, and trial periods that converted to paid plans accumulate quietly. A single monthly pass through bank and card statements catches charges that no longer match what the family actually uses.
Compare actual spending to your budget in each category, not just overall.
A household can appear on track overall while one category runs consistently over budget and another runs under. Category-level review reveals which specific areas need attention and which have built-in slack that could be redirected.
Set or update sinking fund contributions at the start of each month.
Irregular expenses are predictable if you think in annual terms. Dividing the expected cost by 12 and setting aside that amount monthly means no large expense arrives without funding already in place.
For families who want a structured method to assign every dollar a job before the month begins, comparing zero-based budgeting with the 50/30/20 rule can help you choose the right framework.
Building in quick wins you can act on immediately
Some budget improvements take weeks to feel. Others take ten minutes and show up on next month's statement. The actions below are in that second category.
Families who travel and want to extend these habits beyond the household will find that the same consistency that works at home also works on the road.
Common traps that undo good monthly habits
Even households with solid budgets can drift off course. Understanding why helps families avoid repeating the same pattern.
The most common issue is treating the budget review as optional during busy months. One skipped month is recoverable. Three skipped months usually means discovering a problem after it has already done damage. Building the review into a fixed calendar event, even a 20-minute one, protects against this.
A second trap is not accounting for irregular expenses. Car registration, back-to-school clothing, and holiday gifts arrive on a schedule, yet many budgets treat them as surprises. Sinking funds solve this by spreading the cost across the months before the bill arrives.
A third trap is keeping the budget a solo exercise. When one adult manages all the finances alone, the other adult may make spending decisions without context. A brief monthly review with both partners present closes that gap. Structural and psychological factors also deserve attention, because overspending is not always a discipline problem.
Families managing home maintenance costs alongside their monthly budget will find practical guidance at Home on a Budget, and vehicle owners can explore cost-control approaches at Affordable Auto Care.
This article is for general informational and educational purposes only and does not constitute personalised financial advice. Consult a qualified financial professional for guidance specific to your household situation.
Smart Family Finance Editorial Team
Smart Family Finance Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile