The Family Budget: A Plain-English Starting Point
New to budgeting as a family? Learn the core concepts, common frameworks, and realistic first steps to take control of your household spending.
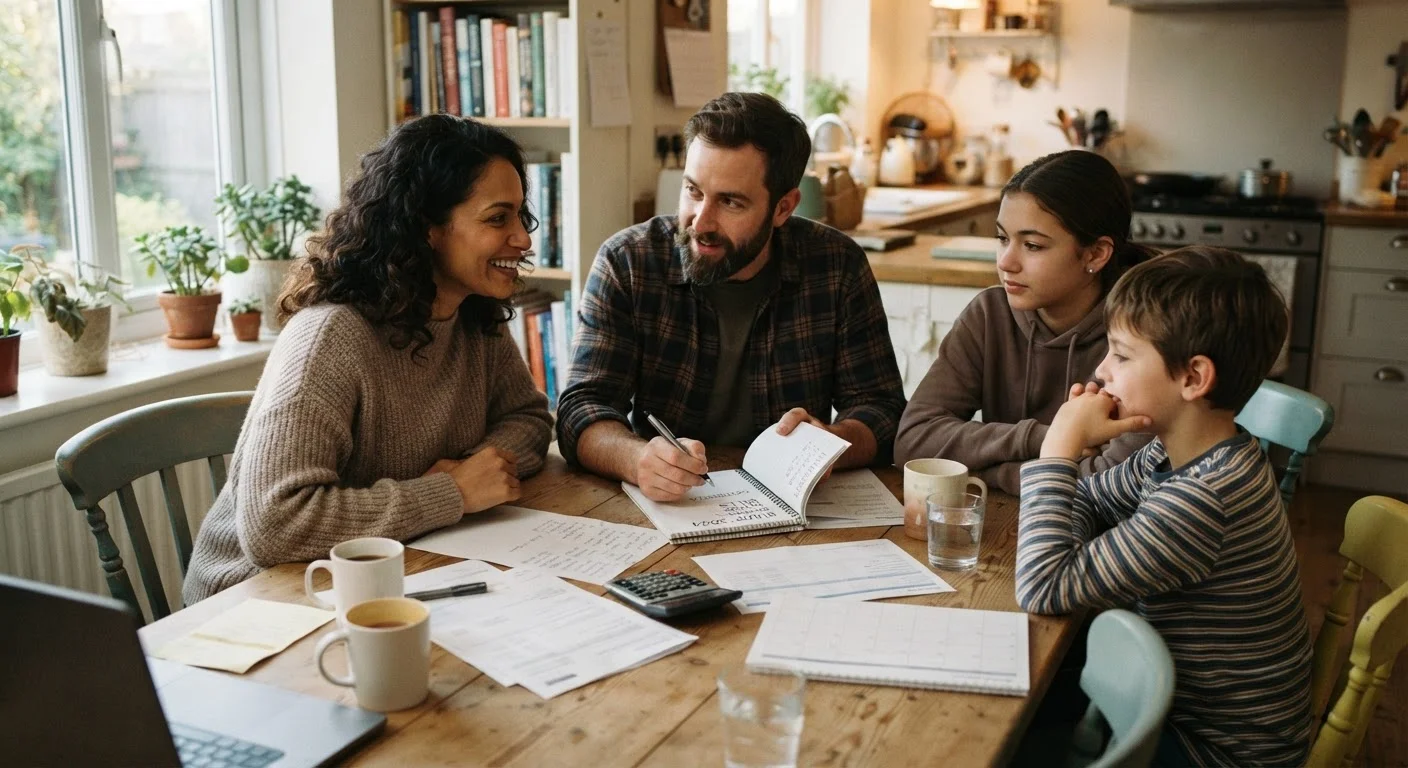
Photo: appropriateanswers.com editorial
—— In This Article
Key Takeaways
- A family budget is a written plan that matches spending to income before the month begins.
- You need three numbers to start: total take-home income, fixed expenses, and variable expenses.
- Popular frameworks like the 50/30/20 rule give structure but can be adapted to your situation.
- Most budgets fail in the first month due to missing irregular expenses, not bad intentions.
- Reviewing the budget together as a household each month is what makes it stick over time.
What a family budget actually is
A family budget is a written plan that tells your money where to go before you spend it. It lists what comes in each month, what must go out, and what is left over. That last number is where financial progress happens.
Many households track spending but never build a budget. Tracking tells you what happened. A budget shapes what will happen. The difference matters because it changes whether you are reacting to money or directing it.
A budget does not require perfection or sacrifice. It requires honesty about income and expenses, and a consistent habit of review. The building blocks of a spending plan article covers the vocabulary you will encounter as you build yours.
Take-home income
The money your household actually receives after taxes and other payroll deductions. This is the number to use when building a budget, not your gross or pre-tax salary.
Fixed expense
A cost that stays the same every month regardless of your behavior, such as a mortgage payment or car loan installment.
Variable expense
A cost that changes from month to month and is often within your control, such as groceries, gas, or dining out.
Irregular expense
A cost that does not appear every month but is predictable across the year, such as annual insurance premiums, school fees, or holiday spending.
Discretionary income
The money left over after all necessary expenses are paid. This is the amount available for wants, savings, or extra debt payments.
Zero-based budget
A budgeting method where every dollar of income is assigned to a specific category so that income minus all allocations equals zero.
The numbers you need before you start
Before choosing any framework, gather three sets of figures.
- Take-home income: This is what actually lands in your bank account each month after taxes and payroll deductions. Use net income, not gross.
- Fixed expenses: Costs that are the same every month, such as rent or mortgage, insurance premiums, and loan payments. These are non-negotiable in the short term.
- Variable expenses: Costs that change month to month, such as groceries, utilities, fuel, clothing, and dining out. These are where most families find room to adjust.
One category people frequently miss is irregular expenses: costs that do not appear every month but are predictable across the year. Car registration, school supplies, holiday gifts, and annual subscriptions all count. Add these up for the year, divide by 12, and include that monthly average in your plan. Forgetting irregular expenses is the single most common reason a first budget falls apart.
Common budgeting frameworks
Several frameworks have earned wide use because they give households a starting ratio rather than requiring them to invent one from scratch.
The 50/30/20 rule
This approach suggests directing roughly 50% of take-home income toward needs, 30% toward wants, and 20% toward savings and debt repayment. It is flexible enough to adapt to most income levels and works well as a first structure. The zero-based budgeting vs. the 50/30/20 rule article compares this approach against an alternative in more detail.
Zero-based budgeting
Every dollar of income gets assigned a category until the remaining balance is zero. Nothing sits unallocated. This approach takes more time each month but leaves no ambiguity about where money is going.
Envelope or category budgeting
Variable spending categories each get a set amount per month. When a category is empty, spending in that area stops until the next month. This works especially well for households that overspend in specific areas like dining or entertainment.
No framework is universally correct. The one that fits your income pattern, household size, and willingness to track is the one worth using.
Your first month: practical first steps
Start with a single month of real bank and credit card statements. Categorize every transaction, even the ones that feel embarrassing. This exercise usually surprises households because actual spending rarely matches what people estimate from memory.
Write out your income and your fixed expenses first. Subtract fixed expenses from income. What remains is available for variable spending, irregular expenses, and savings. If the number is smaller than expected, that is useful information, not a failure.
Write it down before the month starts
A budget made after spending has already occurred is a spending report, not a plan. Even a rough written plan created a few days before the month begins gives you a decision-making reference that memory alone cannot provide. Paper, a spreadsheet, or an app all work equally well as long as the plan exists before you start spending.
Set a specific day each month, the same day if possible, to sit down and compare what you planned against what actually happened. This monthly review is what turns a budget from a document into a habit. The monthly money habits article outlines low-effort routines that make this review consistent.
Budgeting also connects to other household goals. Families working to reduce home costs will find guidance in the Home on a Budget hub, and those planning family trips can apply the same planning discipline covered in stretching a family travel budget.
This article is for general informational and educational purposes only. It is not personalized financial advice. Consult a licensed financial professional for guidance specific to your household's situation.
Where budgets break down and how to recover
Most household budgets do not fail because of poor intentions. They fail for a few predictable reasons.
- The plan did not account for irregular expenses, so an unexpected but foreseeable cost breaks the whole structure.
- One partner felt excluded from the process and does not feel ownership over the numbers.
- The categories were too broad to be actionable, or too narrow to be sustainable.
- A genuine income disruption or unexpected expense occurred and no recovery plan existed.
When a budget month goes wrong, the response that works is a short review, not abandonment. Identify which category broke, decide whether it needs a higher allocation going forward or was a one-time event, and adjust. A budget is a working document, not a final verdict on your spending character.
Health costs are one category that catches many families off guard. The Health Savings Accounts primer explains one option that eligible families can use to plan for medical expenses within their budget.
Frequently Asked Questions
Smart Family Finance Editorial Team
Smart Family Finance Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile