Health Savings Accounts Explained: A Plain-Language Primer for Families
What a Health Savings Account is, how it works alongside a high-deductible plan, and the general tax advantages it may offer eligible families.
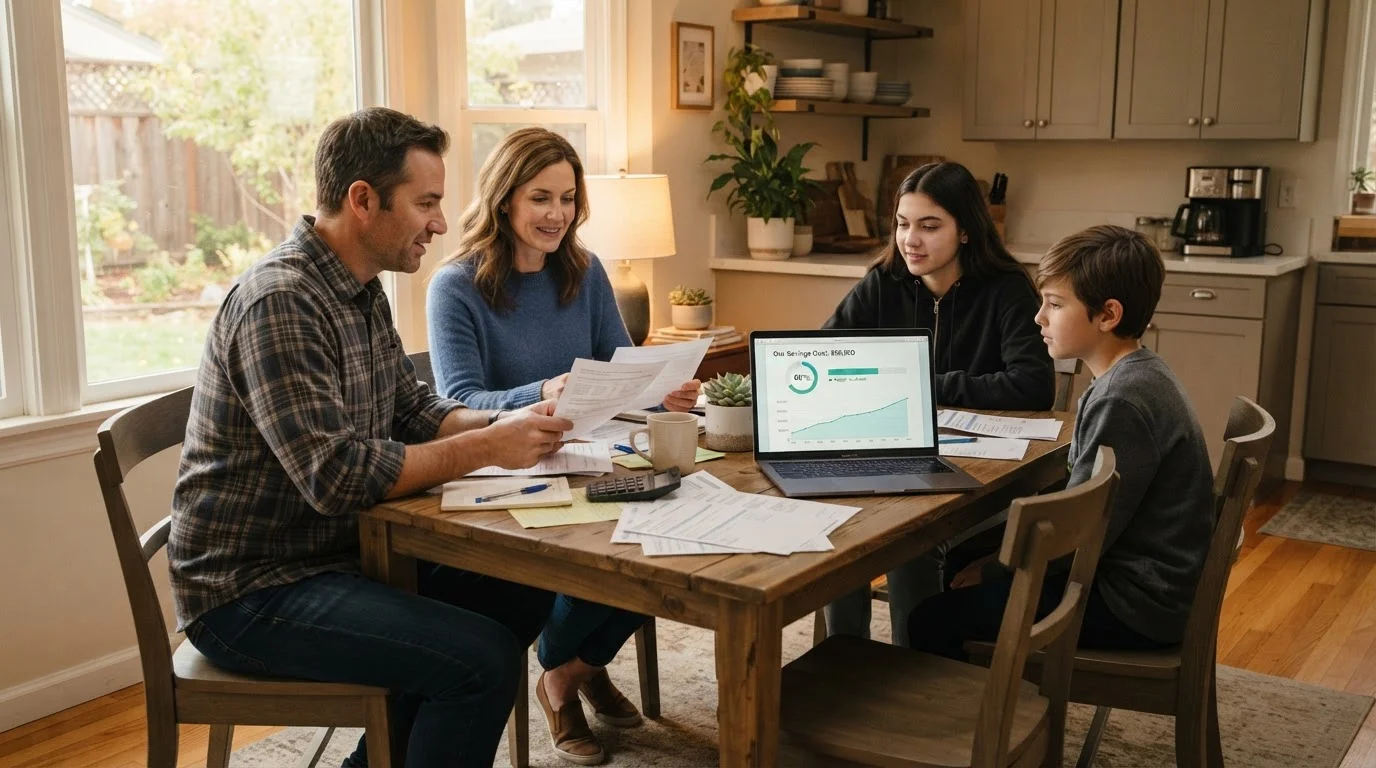
Photo: appropriateanswers.com editorial
—— In This Article
Key Takeaways
- An HSA is only available to people enrolled in a qualifying high-deductible health plan.
- Contributions, investment growth, and withdrawals for eligible expenses are all generally free from federal income tax.
- Unused HSA funds roll over each year and stay with you even if you change jobs or insurers.
- After age 65, HSA funds can be withdrawn for any purpose, though non-medical withdrawals become subject to income tax.
- Families should confirm their plan qualifies and review IRS contribution limits before opening an account.
What an HSA actually is
An HSA is a savings account that comes with three federal tax advantages: contributions reduce your taxable income, money in the account grows tax-free, and withdrawals for qualified medical expenses are not taxed. These three layers together make the HSA one of the few accounts in the U.S. tax code with this combination of benefits.
To open and fund an HSA, you must be enrolled in a high-deductible health plan. The IRS defines specific dollar thresholds for what counts as an HDHP each year, so it is worth confirming your plan qualifies before contributing. You cannot be enrolled in Medicare, claimed as a dependent on someone else's return, or covered by a non-HDHP plan at the same time and still make contributions.
HSAs can be offered through an employer's benefits program, or opened directly through a bank or financial institution that administers them. The account is yours regardless of where it originates.
This article provides general financial information only and is not personalized financial, tax, or legal advice. Consult a qualified professional about your specific situation.
How contributions and withdrawals work
Each year, the IRS sets a maximum amount families can deposit. Contributions can come from you, your employer, or both, but the combined total cannot exceed the annual limit. Amounts contributed by an employer are typically not included in your taxable income, and amounts you contribute yourself are deductible on your federal return even if you do not itemize.
Withdrawals for qualified medical expenses are tax-free at any age. Qualified expenses include most costs not covered by insurance: deductibles, co-pays, dental care, vision care, prescription drugs, and a range of other items listed in IRS Publication 502. If you withdraw funds for a non-qualified purpose before age 65, the amount is added to your income and subject to a 20% penalty.
$8,300
2024 IRS family HSA contribution limit
The IRS set the 2024 family contribution limit at $8,300, with an additional $1,000 catch-up allowed for account holders aged 55 and older.
$1,600
2024 minimum HDHP deductible for self-only coverage
The IRS requires a minimum annual deductible of $1,600 for self-only coverage and $3,200 for family coverage for a plan to qualify as an HDHP in 2024.
After age 65, that penalty disappears. Non-medical withdrawals are then taxed as ordinary income, much like distributions from a traditional retirement account. Medical withdrawals remain tax-free. This flexibility is one reason financial planners often describe a well-funded HSA as a supplemental retirement tool, though that framing depends on individual circumstances and a conversation with a licensed advisor.
The tradeoff: high-deductible coverage
Families considering an HSA need to weigh the tax advantages against the coverage structure of an HDHP. Because HDHPs carry higher deductibles, you pay more out of pocket before insurance begins covering costs. This setup works better for families who are generally healthy and can afford to cover routine medical expenses in a given year.
For families with ongoing medical needs, frequent specialist visits, or children who require consistent care, an HDHP paired with an HSA may not reduce total spending compared to a lower-deductible plan with higher premiums. The math varies by family and by the specific plans available through an employer or marketplace. A licensed insurance professional or benefits counselor can help you compare total annual cost scenarios.
Preventive care is typically covered at no cost under HDHPs, as required by federal law for in-network services. Annual wellness visits, recommended immunizations, and certain screenings generally do not count against the deductible. This matters because maintaining those habits supports long-term health without drawing down HSA funds. For more on how this fits a broader household financial picture, see how families organize spending priorities.
Practical steps for families exploring an HSA
Start by confirming that your current or prospective health plan qualifies as an HDHP under current IRS definitions. Your plan documents or HR department can confirm this. If the plan qualifies, look into what institution holds or would hold the account, and whether your employer contributes any amount on your behalf.
Decide how much to contribute based on your expected medical costs for the year and your capacity to save. Contributing the full annual limit is not required, and smaller consistent contributions still generate tax savings. Pairing HSA planning with a broader household budget makes the decision more concrete. The framework in a plain-English family budget starting point can help ground that process.
Keep records of all medical expenses paid out of pocket, even if you choose to pay them from other funds and leave the HSA untouched. The IRS does not require you to reimburse yourself immediately, so some families accumulate receipts and reimburse themselves later, effectively letting the account grow. Consult a tax professional before using this approach to make sure your records meet IRS documentation standards.
Building HSA savings alongside an emergency fund covers two different risks: unexpected health costs and broader financial disruptions. How an emergency fund functions for a household explains the distinction and why both matter.
Frequently Asked Questions
Family Health Savings Editorial Team
Family Health Savings Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile