Why Families Overspend Despite Good Intentions
Persistent overspending isn't always about bad habits. Understand the structural and psychological traps that quietly drain family budgets every month.
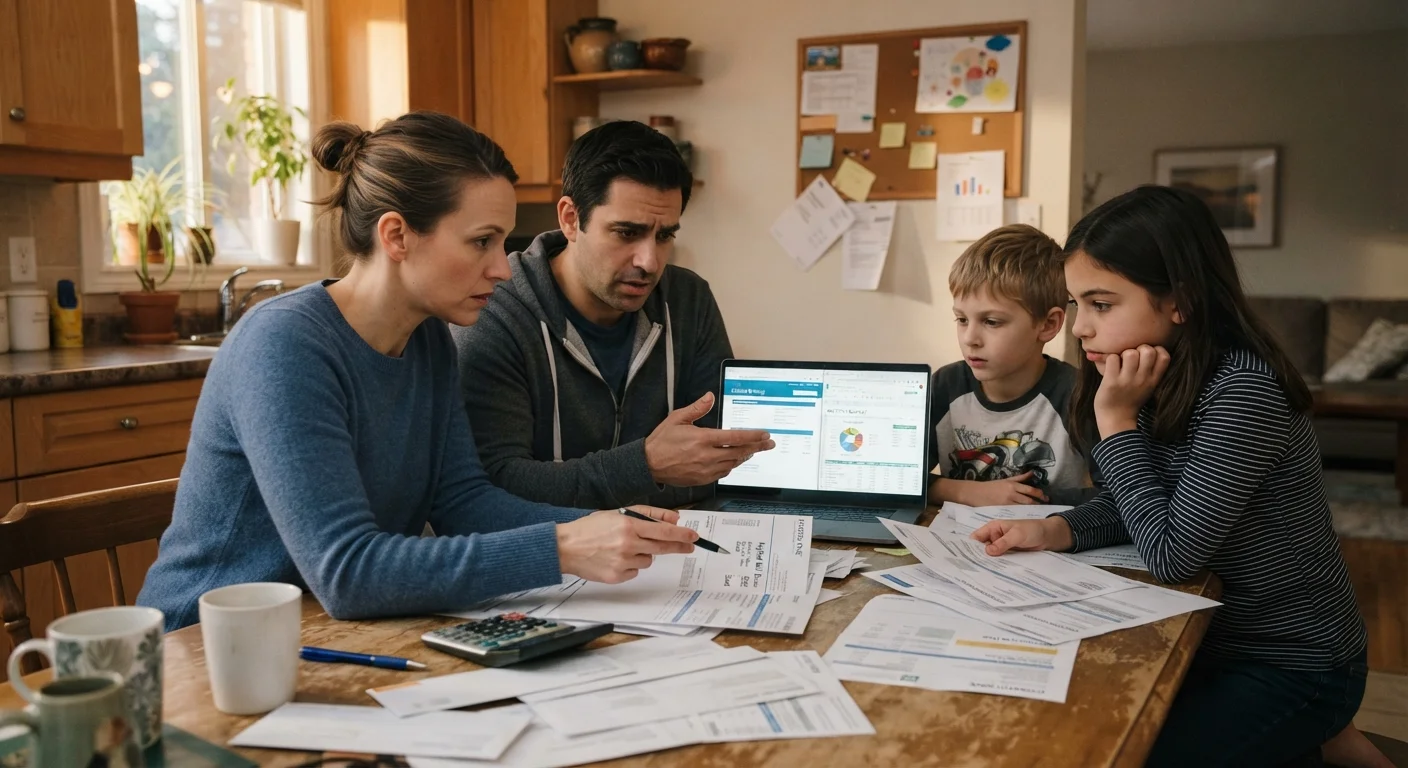
Photo: appropriateanswers.com editorial
—— In This Article
Key Takeaways
- Many families overspend because of structural budget gaps, not a lack of discipline.
- Irregular and forgotten expenses are among the most common culprits of monthly shortfalls.
- Psychological patterns like optimism bias and social comparison quietly inflate spending.
- Simple tracking habits and planned buffer amounts can close most of these gaps.
The gap between intention and actual spending
Most families who overspend are not reckless. They set budgets, they watch the big-ticket items, and they genuinely try. Yet many still end the month with less money than planned. The problem is rarely a character flaw. It is usually a structural one: budgets that miss entire categories, psychological tendencies that distort how people estimate costs, and routines that make spending invisible until the damage is done.
Understanding why these patterns happen is more useful than simply trying harder. The mistakes below appear repeatedly in family budgets, and each one has a practical fix.
Budgeting only for regular monthly bills while ignoring irregular expenses.
Why it happens: Monthly budgets are built around predictable recurring costs, so annual or quarterly expenses like car registration, school fees, or holiday gifts simply do not appear in the monthly view.
Underestimating how much discretionary spending actually costs each month.
Why it happens: Small purchases feel inconsequential in the moment, and families rarely track them in real time. A $6 coffee, a $14 app subscription, and a $25 convenience meal each look minor but compound quickly.
Treating a budget as a one-time document rather than an ongoing tool.
Why it happens: Creating a budget feels like completing a task. Once done, many families file it away and return to spending by feel, which means the budget never adapts to changed income, new expenses, or seasonal shifts.
Allowing lifestyle creep to absorb income increases without building savings.
Why it happens: When household income rises, spending tends to rise with it. Each individual upgrade seems reasonable, but the cumulative effect is that savings rates stay flat even as earnings grow.
Comparing spending to peers rather than to the household's own financial goals.
Why it happens: Spending decisions are influenced by what feels normal within a family's social circle. If neighbors renovate, take elaborate vacations, or drive newer cars, similar choices can feel justified even when the budget does not support them. This is sometimes called social comparison or 'keeping up with the Joneses.'
Skipping a buffer category and leaving no margin for unexpected costs.
Why it happens: When building a budget, families often allocate every dollar to known categories, leaving nothing for the unplanned expenses that occur in almost every month: a medical copay, a car repair, a school supply request.
Why these patterns are hard to break without a system
Awareness alone rarely changes spending behavior. Families who know they overspend on dining out often still do, because the habit is woven into tired weeknights and social obligations. What works is removing the decision from the moment it happens. Allocating a fixed monthly amount for discretionary categories and treating it like a fixed bill gives spending a natural ceiling without requiring willpower at every meal.
The same logic applies to irregular costs. A written annual expense calendar, reviewed each December, turns surprise bills into planned ones. Car registration, school fees, holiday spending, and seasonal home maintenance costs can all be anticipated and saved for in advance. For more on building this kind of routine, see monthly money habits that keep a family budget on track.
Lifestyle creep can be hard to spot in real time
Spending upgrades often feel like reasonable quality-of-life improvements when they happen one at a time. By the time the pattern is visible, it may already be embedded in fixed monthly commitments like subscriptions, loan payments, or lease agreements. Reviewing total fixed obligations as a percentage of take-home pay at least once a year can reveal whether creep has quietly narrowed financial flexibility.
Families who also want to trim spending in specific areas can find related guidance on grocery spending myths and car ownership costs most families overlook. On travel, common vacation overspending habits follow the same structural patterns described here.
This article is for general informational and educational purposes only and does not constitute personalized financial advice. Consult a qualified financial professional for guidance specific to your household situation.
Smart Family Finance Editorial Team
Smart Family Finance Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile